NIFTY | Credit Spread | Expiry Cycle | Time-Decay Strategy
What this algo is trying to do?
Options lose value with every passing day, all else being equal, that erosion is called time decay, or “theta.” Theta-Harvest Credit Spread Expiry is built to sit on the side of that decay rather than fight it, using a hedged credit spread that collects premium upfront and lets the passage of time work in its favour through the expiry cycle.
How does the strategy work?
Think about how decorations and diyas are priced in the run-up to Diwali. A week before, shopkeepers can charge a premium because demand is high and time is short. Each day that passes without a sale, that item is worth a little less and the day after Diwali, most of that value is gone entirely, occasion-linked stock being what it is. Someone who sold that stock before its value decayed benefited from the clock ticking, not despite it.
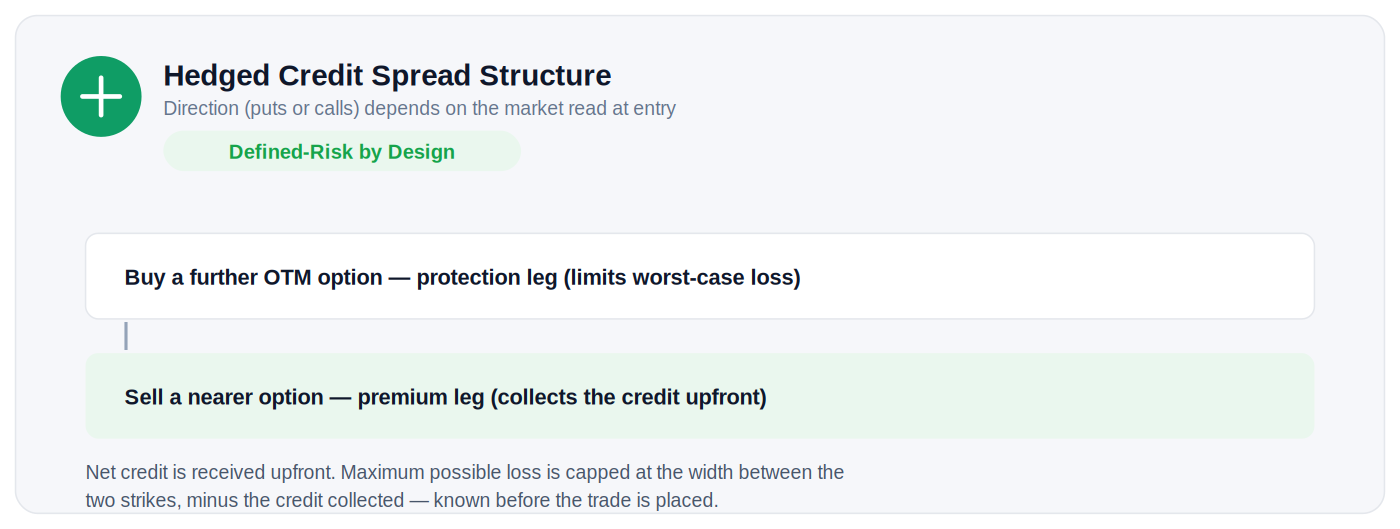
Option premium works on a similar clock. As an option approaches its expiry date, the portion of its price tied purely to “time left on it” shrinks, slowly at first, faster as expiry nears. Theta-Harvest is structured to be the seller in that transaction: it collects the premium through a hedged credit spread — selling one option and buying a further out-of-the-money option against it, which caps the worst-case loss upfront — and then stays positioned through the expiry cycle while decay works in its favour.
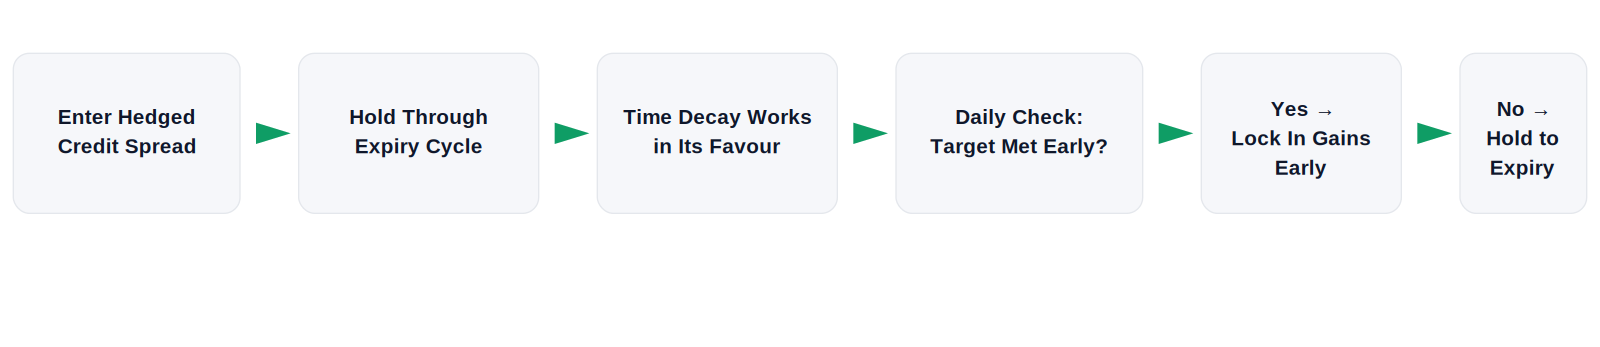
What makes this strategy a bit different from a purely mechanical “sell and wait” approach is how it handles the exit. It isn’t required to hold every position all the way to expiry. If a trade captures a large chunk of its expected profit earlier than expected, the algorithm can choose to book that gain and exit early rather than waiting around for the last bit of premium — the same instinct as a vendor who’s happy to sell out by the afternoon at a fair price instead of holding out till closing time for a slightly better one, and risking not selling at all.
Risk Management
-
The credit spread structure means every trade has a known worst-case loss from the moment it’s placed — there’s no naked, uncapped side to the position.
-
A stop-loss and a target profit level are both defined upfront, so the algorithm isn’t making exit decisions on the fly.
-
The strategy checks market hours, trading windows, and expiry-specific conditions before entering, to avoid positioning right before conditions it isn’t built to handle.
-
Around half of all trades are profitable — this isn’t a strategy that wins on volume of trades; it’s built so that its process, applied consistently across many trades, works out favourably over time.
Understanding the risk
Every premium-selling strategy carries the same basic exposure: if the market moves sharply against the position before time decay can help, losses can build faster than the credit collected offsets them. That’s the trade-off behind every hedged credit spread, including this one.
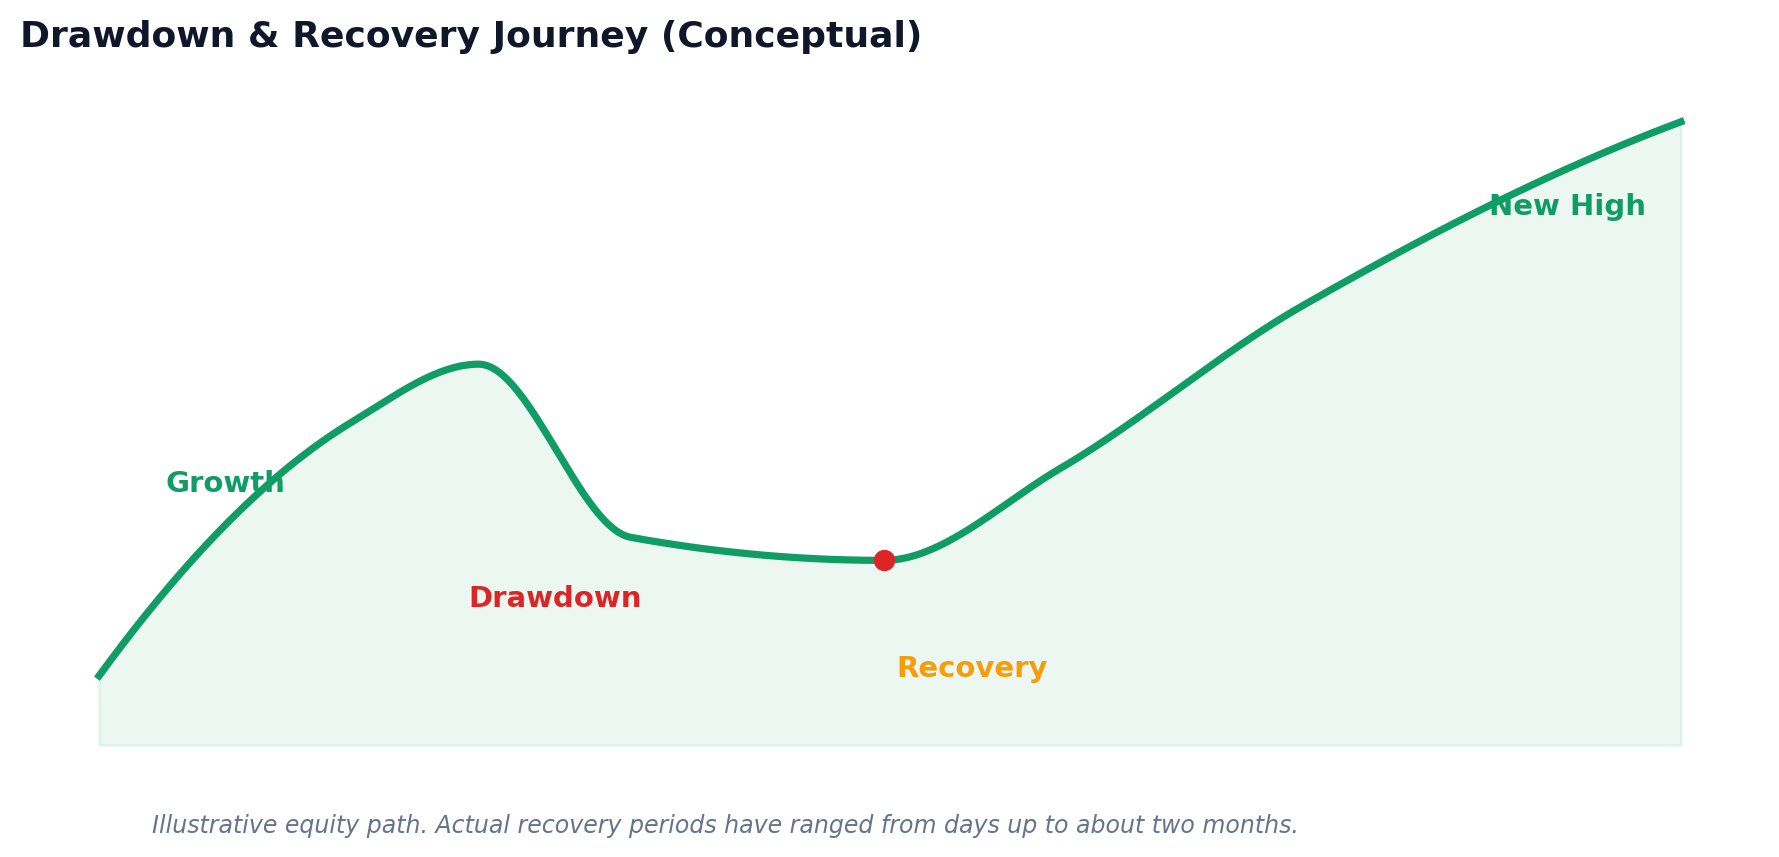
Relative to some other credit-spread algos on the platform, Theta-Harvest’s drawdowns have tended to be shallower and its recoveries shorter — but “High” risk still means real risk. A string of losing trades, or a stretch where the market doesn’t cooperate with the expiry-cycle setup, is a normal part of how this strategy behaves, not a sign that something is broken.
Combining with other algos
No single algo — including this one — is immune to a bad stretch. One way investors manage that on the Stratzy platform is by holding Theta-Harvest alongside other algos rather than allocating to it alone.
The reasoning is simple: if two strategies don’t tend to lose money at the same time, combining them can smooth the portfolio’s overall returns curve, even without either strategy individually becoming less risky. Stratzy’s Combine Algos tool shows the historical correlation between Theta-Harvest and other algos on the platform — and in practice, its correlation with most other credit-spread strategies has run fairly low. That means the periods when Theta-Harvest is under pressure haven’t necessarily lined up with the periods when other algos are, which is the basic condition needed for diversification to actually help.
We can also see from the below chart how the volatility of Theta-Harvest is lowered when combining multiple strategies like Zen Credit Spread and Damper Credit Spread, thus making the returns curve smoother.
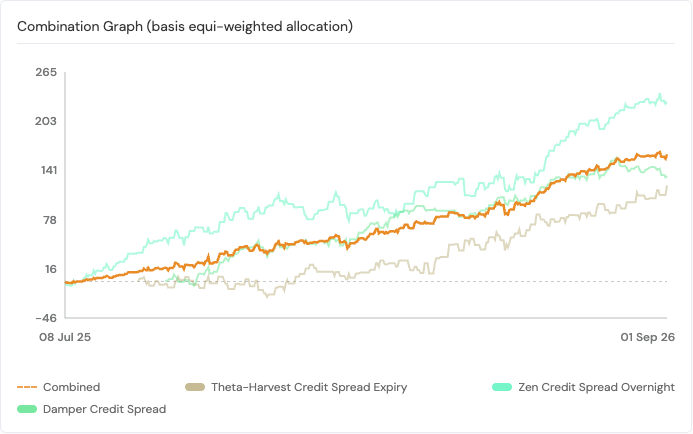
This doesn’t change Theta-Harvest’s own risk profile in isolation — its standalone drawdown behaviour stays what it is. What it can change is how bumpy the ride feels at a portfolio level, if it’s held as one part of a spread of algos rather than as a single, concentrated bet.
Before finalising an allocation, it’s worth checking the Combine Algos view on the platform to see how Theta-Harvest has moved alongside other strategies, rather than looking at it in isolation.
Strategy Snapshot
| Metric | Value |
|---|---|
| Underlying | NIFTY |
| Strategy Type | Hedged Credit Spread |
| Holding Period | Through the expiry cycle, with flexibility to exit early on target |
| Favourable In | Directional moves |
| Average Frequency | ~3 trades/week |
| Risk Level | High |
| Risk : Reward | 1.38 |
| Recovery Time (Average / Maximum) | 15 Days / 62 Days |
Who is this strategy suitable for?
Theta-Harvest Credit Spread Expiry is best suited for investors who:
-
Understand how option premium decays over time, and want a strategy built to be on the receiving side of that decay.
-
Are comfortable with a High risk allocation and the drawdowns that come with any premium-selling strategy, even a hedged one.
-
Value a defined-risk approach — every trade has a known worst-case loss before it’s placed.
-
Appreciate a strategy that doesn’t mechanically hold to expiry no matter what, but locks in gains when the opportunity has already played out.
-
Are looking to diversify a broader options portfolio rather than treat this as a single, concentrated allocation.
This is not a strategy for anyone expecting zero drawdowns, or looking for a purely buy-and-hold, low-monitoring investment.
Final Thoughts
Theta-Harvest Credit Spread Expiry takes a simple, well-understood market mechanism — option time decay — and structures a hedged, defined-risk way to sit on the favourable side of it through the expiry cycle, while staying flexible enough to lock in gains early when the opportunity allows.
It carries a High risk rating, and that risk is real: drawdowns happen, and no premium-selling strategy avoids the occasional sharp move against it. Weigh the mechanics and risk profile described here against your own risk appetite and time horizon, and consider viewing it alongside other algos on the platform rather than in isolation.