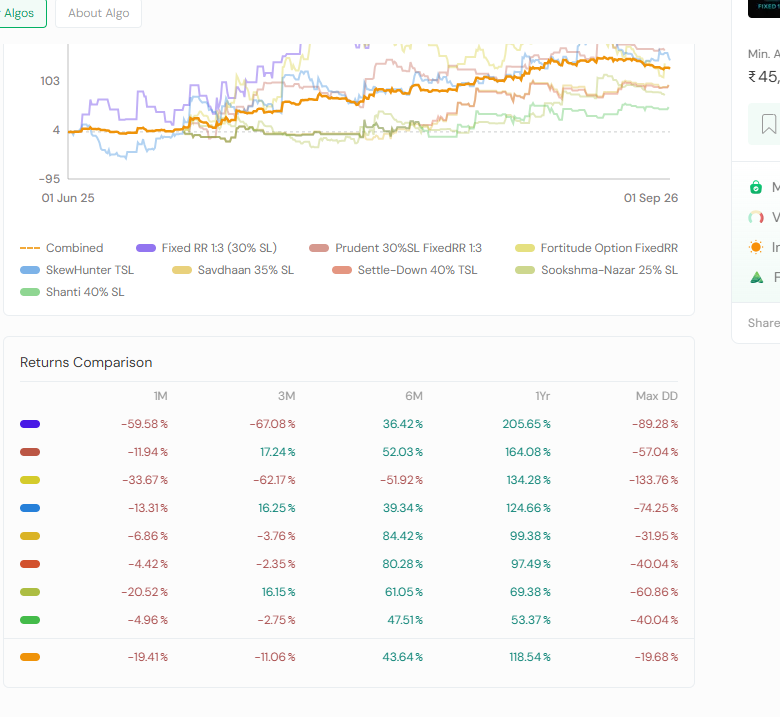
I have attached screen shot of all OPTION BUYING strategies which were working super over the last year
(See return of all these strategies in 1 Year column). All these strategies are in loss for last one month. (see one month return). Whether Stratzy team evaluated impact of CAS on their strategies.
1 Like
Hi,
Yes, We are keeping track of the changing regime. A microstructure change as big as CAS has affected market behavior.
As market evolves, we need to keep evolving our algos as well (So do keep an eye out for new algos which are launched)
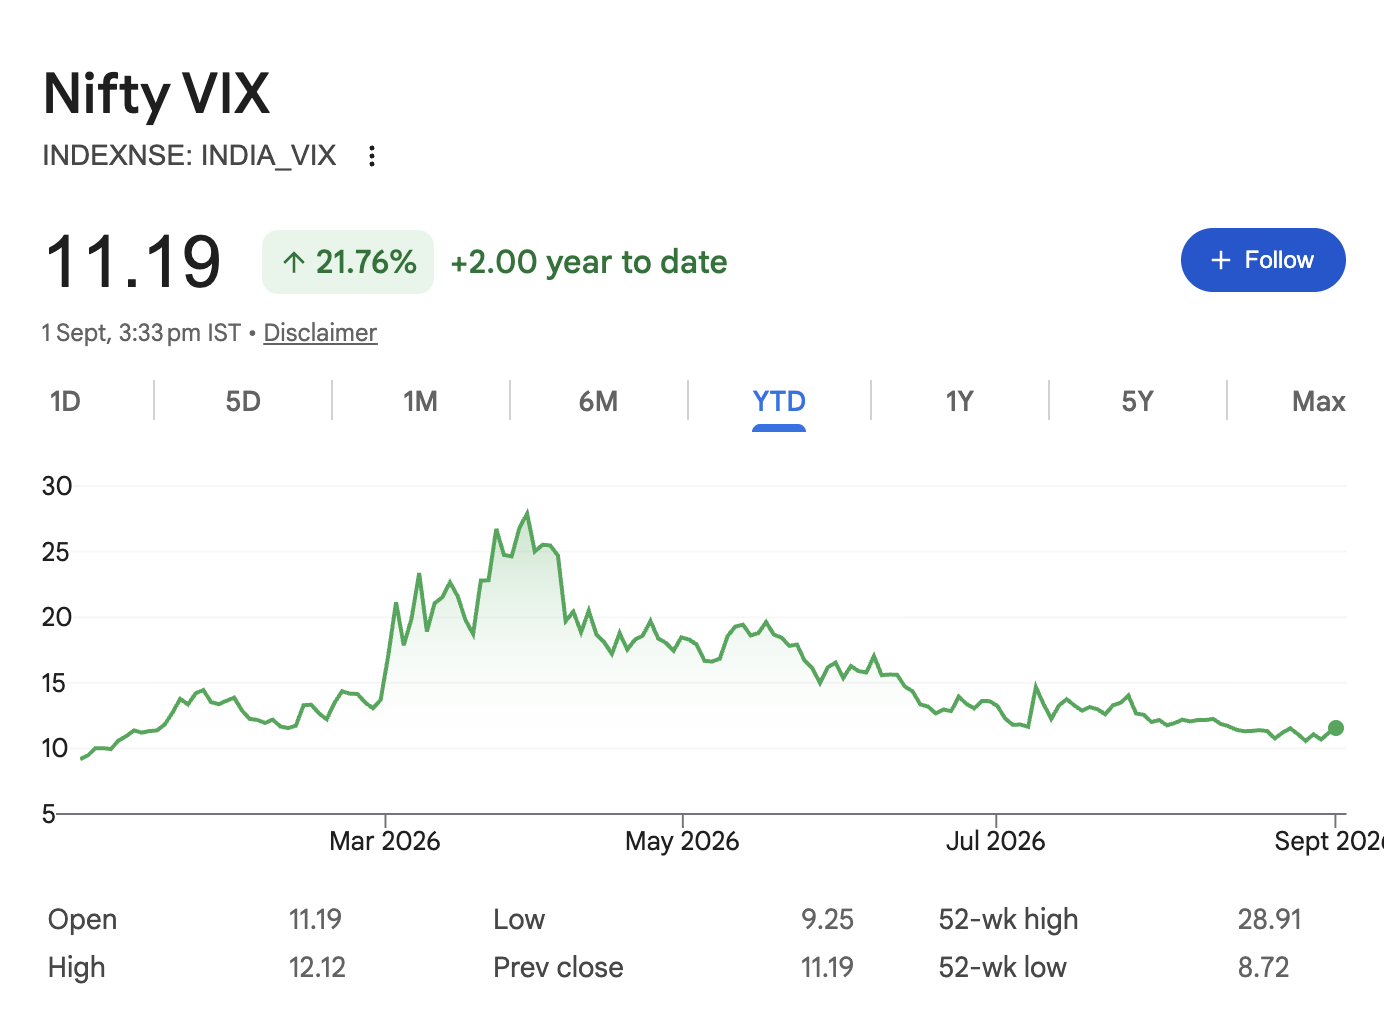
That being said, the current environment has been very low VIX
At start of the year January we were at 9 VIX , and it made a peak of 27 VIX in March. Since then we have quietly declined to 11 VIX in 6 months.
We need an increasing VIX environment to see more options buying opportunities in the market which algos can capture.
1 Like
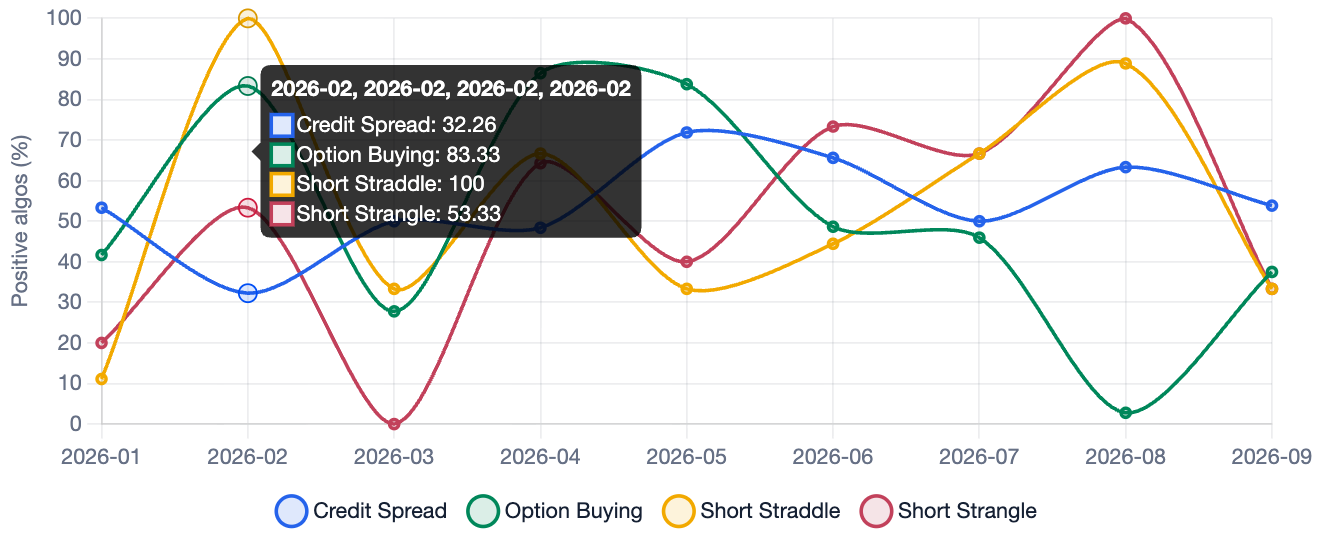
built a system to queries through AI on our Stratzy website and answer queries, if we see the data during March 26 when VIX was high then short vol algos like strangle algos also reached 0% positive algos as we are seeing now with options buying
If you have more questions/queries on how the algo pool is behaving post here 
1 Like
Can you elaborate more in detail?
@mohit.bhandari The chart you’re referring to suggests that Option Buying algos’ positive-algo percentage increased sharply in August (from around 0–5% to ~40%). If that’s correct, then I’m a little confused because the top two OB algos, SkewHunter, delivered a negative return in August, and Fixed RR performed even worse—it was its worst month.
Could you please clarify how the Option Buying chart is showing such a significant improvement in August, despite the actual performance of these top OB algos being negative?
Also, which OB algos are contributing so positively that they are effectively nullifying the impact of the huge negative returns from SkewHunter and Fixed RR, and taking the overall Option Buying figure so sharply upward in August? Is there something I’m misunderstanding about what this chart represents?
The chart is of the % of algos which were positive that month with respect to the total algos in that category.
So if Credit spreads has 50 algos for example and 40 of them have been positive the % would be 40/50*100 = 80% of algos in that category were positive
The graph is a month on month graph of different category and the % of positive algos in those category.
Now this data combined with the VIX can show how we need an increasing VIX environment for options buying to be fruitful. As that regime helps OB algos.
1 Like
Options buying category is the green line here, You can see it made a peak of 80% in Feb and April, May to fall to 0% in August.
We have seen the red line short strangle category also reach 0% in March 2026 which was the highest VIX era.
This doesn’t consider the the magnitude of positive/negative pnl but instead just showing the % of positive pnl algos in that category for that month
Please check the chart, In August there is no jump in OB
1 Like
So kindly stop OB algos in this type of condition or do some fruitful changes in existing algos. We are in huge loss in OB alogs.
Understood ur point. If OB works only in high/rising vix regime, cant you stop generating signals for OB algos in low vix environment. A condition with repsect to VIX should be incorporated in Algo logic.
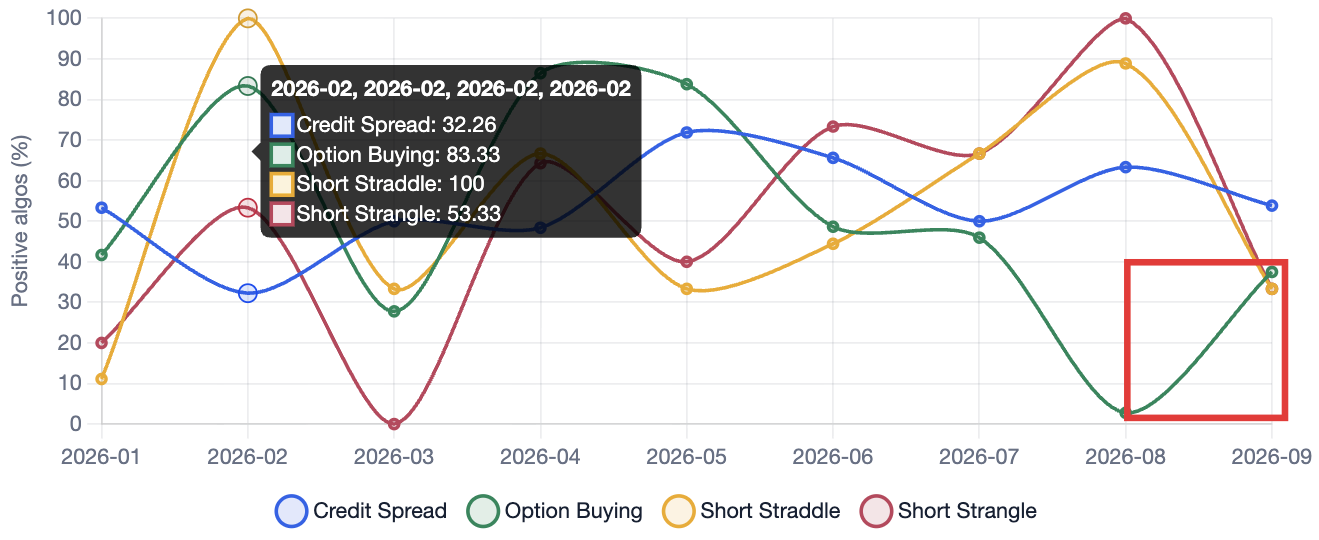
@mohit.bhandari I’ve highlighted the area with a box, and it clearly shows that there is a significant jump in Option Buying (OB) from August to September.
Also, I want to ask you something. If you already understand that OB algos need high VIX to capture meaningful market opportunities, then don’t you think high VIX should be the first parameter for your OB algos before taking any trades?
However, all your OB algos seem to be taking trades aggressively even in such a low-VIX environment, and we are seeing SLs getting hit almost every day.
Please check the current DD of SkewHunter and Fixed RR once. Both algos have already wiped out their entire allocated capital.
If a high-VIX parameter had been implemented, how much of users’ hard-earned money could have been saved?
And one more thing I genuinely don’t understand — is generating brokerage for the broker more important than protecting users from losses? Because if all your OB algos are continuing to take trades every day even in such a low-VIX environment, I honestly fail to understand the logic behind it.
1 Like
I completely agree with this concern. As an experienced investor, I believe it is unfair for users to continue bearing losses without clear communication from Stratzy. If algorithms that delivered strong historical performance are no longer generating returns, they should be reviewed and updated according to current market conditions.
There is a huge gap between the past and present performance of algorithms such as Skew Hunter. Why is Stratzy not addressing this issue? We have continued running these algorithms and even added capital to maintain margins, trusting that the mathematical models would recover once market conditions changed. However, there has been no clear communication regarding their performance, future outlook, or any planned improvements.
Many small investors have suffered significant capital erosion due to these OB algorithms. Can someone from Stratzy provide a transparent view on whether investors should continue with these strategies or consider exiting them? Clear guidance would be greatly appreciated, especially by those who are continuing to deploy additional capital in the hope of recovering past losses.
2 Likes
Agree . I don’t see any adaption happening . The justification given is not convincing .