This week was a good reminder that market direction alone doesn’t tell the full story.
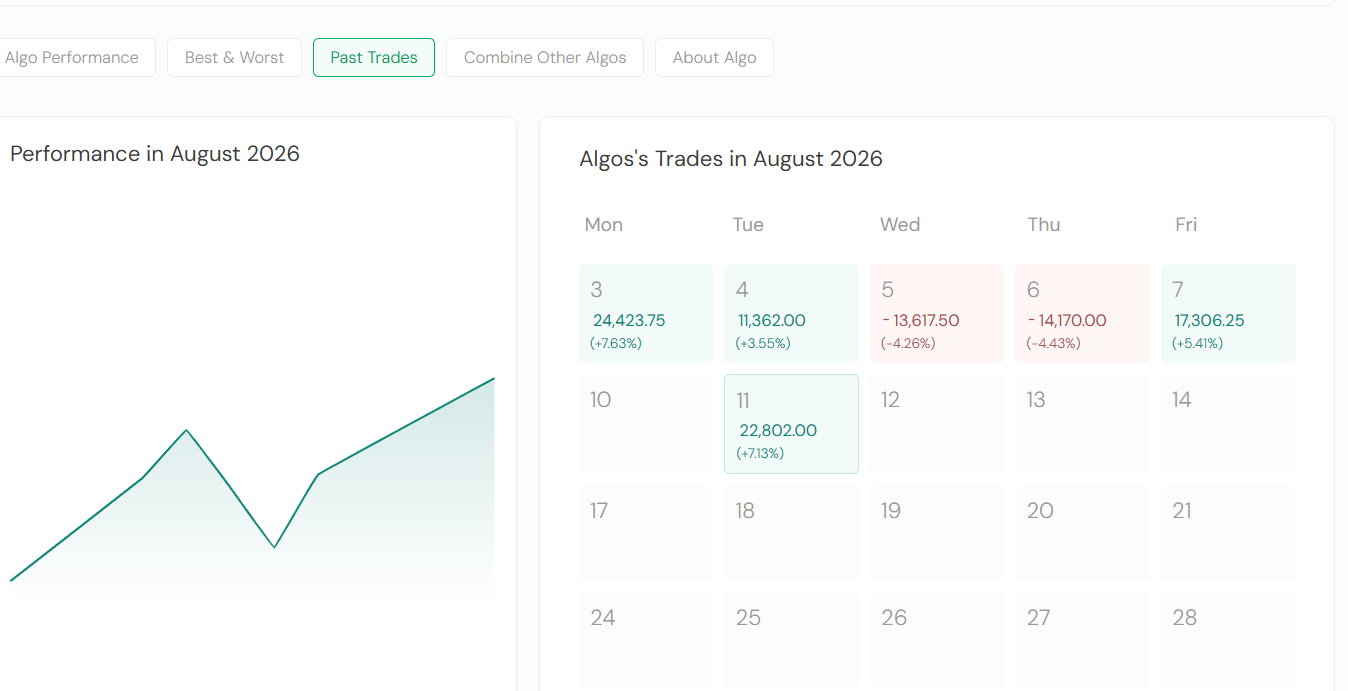
The Nifty remained under pressure for most of the period, but volatility stayed relatively contained. At the same time, the new closing-auction mechanism continued to create some unusual end-of-day price behaviour.
While reviewing the algo dashboard, the biggest takeaway for me was simple:
The same market can create very different outcomes for different strategy structures.
 Market Snapshot — Quick & Important
- Nifty 50: 24,176 → 24,472
- Bank Nifty: ~57,000–57,500 zone
- India VIX: 12.06 → 11.86
Nifty closed at 24,176 on 5 August and 24,472 on 11 August. India VIX moved from 12.06 to 11.86 over the same period.
 What this tells us
Nifty remained weak but volatility did not explode.
That distinction is important for option strategies.
On 11 August, rising crude prices and renewed geopolitical uncertainty pressured equities, while India VIX actually declined to around 11.86.
So this was not a classic panic-volatility week.
 What Mattered in the Market
 New Closing Auction System
The newly introduced closing-auction mechanism continued to attract attention after sharp end-of-day moves around the previous expiry. Reuters reported unusually sharp Nifty swings linked to the new mechanism.
For algo traders, this is particularly relevant because execution and closing-price behaviour can directly affect option strategies.
 Crude Oil Came Back Into Focus
By 11 August, crude was approaching the $90/barrel mark, with fading hopes of a US-Iran peace agreement adding pressure to Indian equities through the import bill, inflation and margin concerns.
 Index Rebalancing News
Another notable development: BSE is set to replace Wipro in the Nifty 50 from 30 September 2026, following the latest index review.
Not an immediate market-moving event for this week, but definitely something worth keeping on the radar for index-linked portfolios.
 Credit Spread Strategies
This category had a very mixed week.
Some strategies delivered strong positive returns, while others faced meaningful drawdowns.
| Strategy | Weekly Performance |
|---|---|
| Delta-Shift Credit Spread Expiry | +16.36% |
| Ratio-Weave Credit Spread Expiry | +13.87% |
| Theta-Harvest Credit Spread Expiry | +12.48% |
| Ratio-Hunter2 Credit Spread Exit-Early | +9.02% |
| IV-Imbalance Credit Spread Overnight | +9.08% |
| Ratio-Fluxer Credit Spread Expiry | +7.22% |
| Curve-Whisper Credit Spread Overnight | +5.01% |
| Zen Credit Spread Overnight | +4.03% |
| Mathematician’s Credit Spread Overnight | +3.85% |
| Gamma-Fluxer Credit Spread Overnight | +3.32% |
| Curvature Credit Spread Overnight | +3.10% |
| Delta-Ripple Credit Spread Overnight | +2.65% |
| Damper Credit Spread | +2.05% |
| Wave-Return Credit Spread Overnight | +1.38% |
| Drifting Credit Spread Overnight | +1.18% |
| Hamilton’s Credit Spread | 0.00% |
| E-QUEUE Credit Spread Overnight | 0.00% |
| Ripple-Return Credit Spread Expiry | 0.00% |
| Delta-Leverage Credit Spread Overnight | 0.00% |
| Ratio-Return Credit Spread Exit-Early | 0.00% |
| Warp-Drive Credit Spread Exit-Early | 0.00% |
| Ratio-Ripple Credit Spread Exit-Early | 0.00% |
| Deep-Rooted Credit Spread Overnight | 0.00% |
| Sookshma-Chaal Credit Spread Overnight | 0.00% |
| Sensex Credit Spread Exit-Early | 0.00% |
| Primal Credit Spread Exit-Early | 0.00% |
| V-Score Credit Spread Overnight | -4.16% |
| Chain-Sync Credit Spread Overnight | -4.52% |
| Vega-Shift Credit Spread Expiry | -4.33% |
| Convex Credit Spread Overnight | -4.83% |
| Delta-Rotation Credit Spread Expiry | -8.60% |
| Theta-Flux Credit Spread Overnight | -16.03% |
| Rolling-Carry Credit Spread Exit-Early | -14.87% |
My observation:
Credit spreads were not uniformly positive. The dispersion between strategies was large — which is exactly why category diversification is not enough; strategy-level diversification matters too.
 Straddle & Strangle Strategies
| Strategy | Weekly Performance |
|---|---|
| Single Rangetrap Straddle | +4.12% |
| Single Tightgrip Straddle | +4.06% |
| Quiet Short Straddle | +3.69% |
| Single Lattice Straddle | +3.05% |
| Single Kurtosis Straddle | +3.02% |
| Expiry Short Strangle | +3.28% |
| Sahi-Nivesh Short Strangle Overnight | +2.84% |
| Market-Pulse Short Strangle Overnight | +2.86% |
| Sidha-Sauda Short Strangle Overnight | +2.73% |
| Chanakya Short Strangle Overnight | +2.50% |
| Homecoming Short Strangle Overnight | +2.43% |
| Carry Forward Strangle | +2.12% |
| Compressed Strangle | +1.92% |
| Fusion Gate (main) · a4cdc5 YAML Strategy | +1.84% |
| Holonomy’s Short Strangles | +1.53% |
| Theta-zone Strangle | +1.35% |
| Premium-zone Strangle | +1.12% |
| Flux Strangle | +1.00% |
| Slow-Climb Short Strangle Overnight | +0.83% |
| Synthesized Gate (main) · 4e2937 YAML Strategy | +0.80% |
| Lattice Short Straddles | +0.75% |
| Bazaar Short Strangle Overnight | +0.73% |
| Blend Rank (main) · 8e15c0 YAML Strategy | +0.49% |
| Intraday Short Strangle | +0.37% |
 Takeaway
The straddle/strangle bucket was remarkably consistent on the positive side this week.
With VIX remaining around the 12 zone, the environment was not hostile to premium-selling structures.
 Option Buying Strategies
This was a very different story.
| Strategy | Weekly Performance |
|---|---|
| Ghar-Aangan 30% TSL | +0.40% |
| Sahas 40% SL | +0.12% |
| Aequitas 25%SL FixedRR 1:3 | 0.00% |
| Nischay 40% TSL | 0.00% |
| Only-Calls 40% TSL | 0.00% |
| Safe-Khel 40% TSL | 0.00% |
| Harbor 33%SL with Partial Target | 0.00% |
| Seed-Fund 40% SL FixedRR 1:3 | -0.15% |
| Thrifty 40% TSL | -0.45% |
| Vacuum GRID (35% SL) | -1.02% |
| Watchful 33% SL Grid | -1.04% |
| Sunrise 33%SL + Partial Target | -2.37% |
| Cornerstone 33%SL + Partial Target | -2.36% |
| Settle-Down 40% TSL | -2.52% |
| Savdhaan 35% SL | -2.58% |
| Shanti 40% SL | -2.52% |
| Wise-Move 25% TSL | -3.91% |
| Chhota-Move 30% SL FixedRR 1:2 | -4.68% |
| Patience 35%SL FixedRR 1:3 | -4.65% |
| Free-Lunch 30% TSL | -4.92% |
| First-Step 25% SL | -4.81% |
| Pillar 35%SL FixedRR 1:3 | -0.88% |
| Aastha 35% TSL | -5.38% |
| Dhyaan 35% TSL | -5.56% |
| Equilibrium 25%SL FixedRR 1:3 | -5.35% |
| Sookshma-Nazar 25% SL | -6.58% |
| Fixed RR 1:3 (30% SL) | -6.82% |
| Aaram-Se 30% TSL | -7.29% |
| Vigil 25%SL FixedRR 1:3 | -7.34% |
| Prudent 30%SL FixedRR 1:3 | -7.75% |
| Burst GRID (30% SL) | -6.95% |
| Burst RR 1:2 (25% SL) | -8.50% |
| Index Sniper | -7.65% |
| SkewHunter | -12.93% |
| SkewHunter TSL | -12.99% |
| Index Scalper | -17.44% |
| Fortuna 30%SL FixedRR 1:3 | -18.87% |
Important observation
This is probably the clearest contrast from this week’s dashboard:
Low volatility + limited directional follow-through can be difficult for option-buying systems.
Several directional systems struggled despite the market not experiencing a major volatility spike.
 My Take as a Wealth Manager
Looking at the complete dashboard, three things stand out to me.
 Same market ≠ same algo outcome
Credit spreads ranged from +16.36% to -16.03%, while option-buying strategies ranged from roughly flat to -18.87%.
So simply saying “this was a good market for credit spreads” would be too simplistic.
Strategy construction mattered.
 VIX stayed relatively calm
India VIX moved from 12.06 to 11.86, and even on the weak market day of 11 August it closed lower.
That helped create a different environment from a high-volatility sell-off.
 Execution is becoming increasingly important
With the new closing-auction mechanism creating unusual end-of-day moves, I think algo investors should pay more attention to execution behaviour, square-off mechanics and how strategies handle the closing window — not just backtested returns. ([Reuters][3])
 Week in One Glance
Best-performing buckets:
Selected Credit Spreads
Straddles & Strangles
More challenging bucket:
Option Buying / Directional Systems
But the bigger lesson is:
Don’t judge an algo by its category. Judge it by how it behaves across different market regimes.
 Why I Keep Sharing the Full Dashboard
As a Wealth Manager, I don’t find it useful to show only the top 5 performers.
The winners and losers both matter.
Because when you’re constructing a portfolio, knowing what struggled is just as important as knowing what worked.
That’s also where the Stratzy Alpha Portfolio approach becomes relevant — instead of depending on one algo or one market view, the focus is on combining different strategy structures with an emphasis on portfolio-level risk management and diversification.
Looking at this week’s numbers:
Would you rather build your portfolio around:
Credit Spreads
Straddles & Strangles
Option Buying
 Or a combination of all three?
And more importantly —
Would you choose an algo because it performed well this week, or because you understand how it behaves when the market regime changes?
Let’s discuss 